Ottawa Has Warned It May Block the Sale of an Argentine Salt Flat. The Seller Says Canada Has No Jurisdiction Over It at All
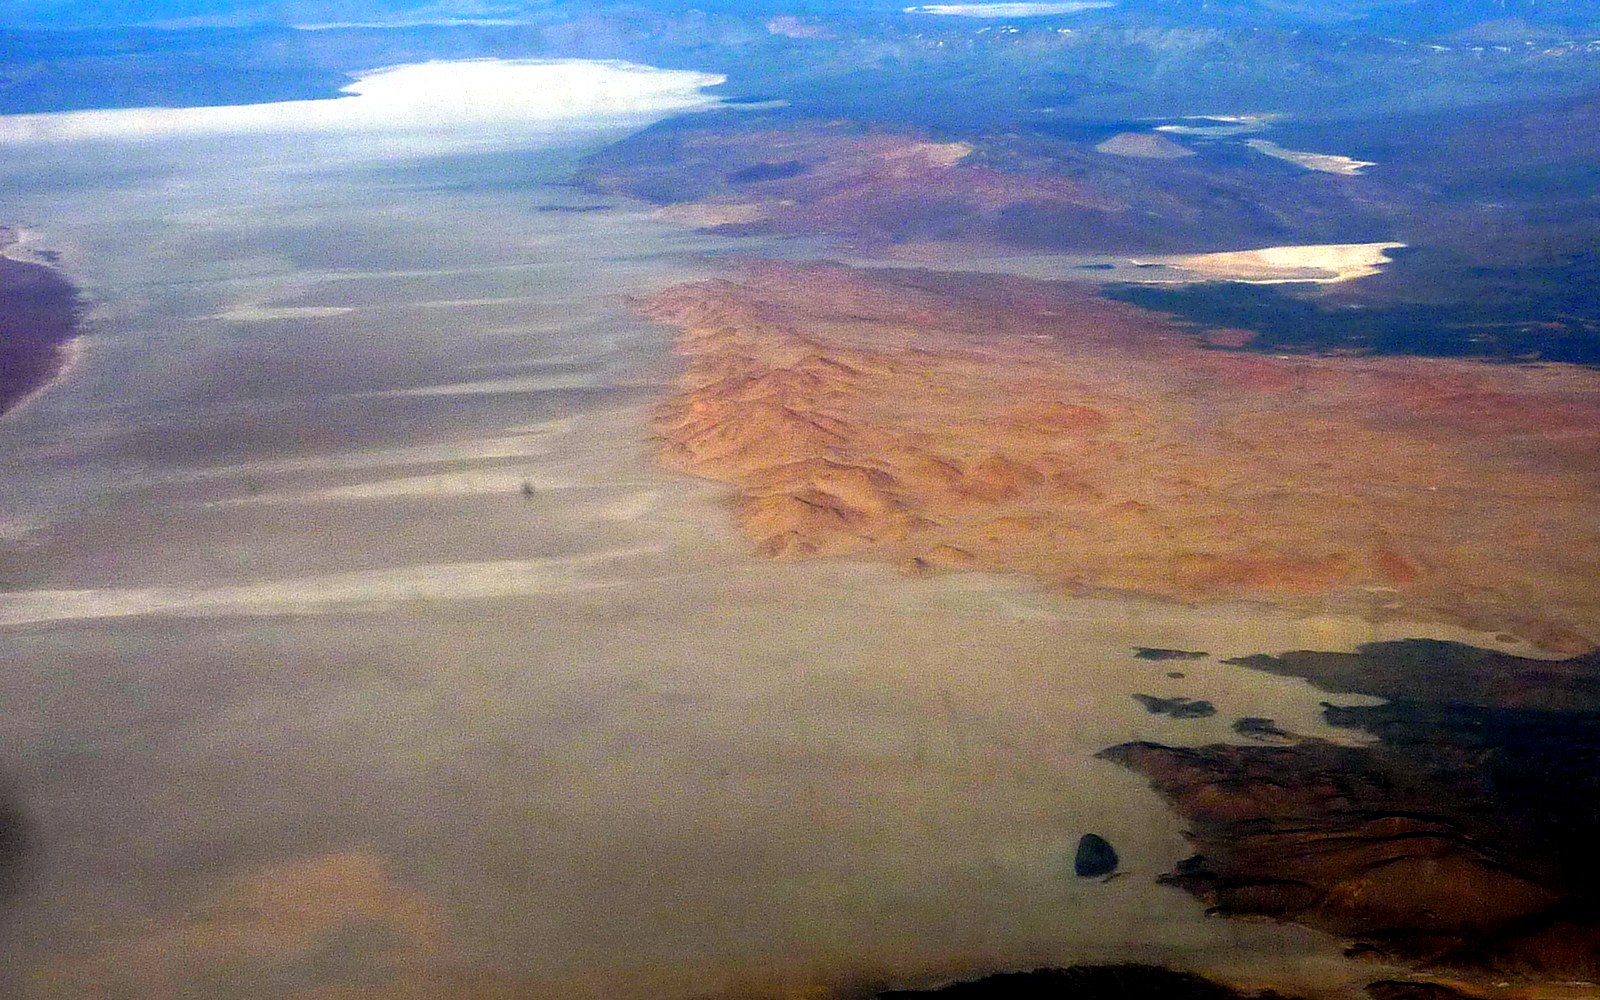
In the week to 18 August 2026, Canada's director of investments issued a notice under subsection 25.2(1) of the Investment Canada Act over the sale of Argentum Lithium to China Union Holdings. Argentum is Lithium Chile's Argentine subsidiary and holds the company's interest in the Salar de Arizaro in Salta province. The notice states there are reasonable grounds to believe the transaction could be injurious to Canadian national security. Lithium Chile disputes that Ottawa has jurisdiction at all, on the ground that Argentum is not a Canadian company and has no assets, employees or place of business in Canada. The regulations give the government 45 days from the notice to order a full review. As of the reporting, no such order had been made. The buyer holds rights under a Canada-China investment treaty that expressly excludes this category of decision from arbitration.
What Ottawa actually did
China Union Holdings agreed in December 2025 to acquire all outstanding shares of Argentum Lithium, the subsidiary through which Lithium Chile holds its interest in the Salar de Arizaro. The reported consideration is 175 million dollars. The transaction still requires outbound direct investment approval from Chinese regulators, which is a separate process running on its own clock in Beijing.
In the week to 18 August 2026, Canada's director of investments issued a notice under subsection 25.2(1) of the Investment Canada Act. The provision requires the Minister to send such a notice where there are reasonable grounds to believe that an investment by a non-Canadian could be injurious to national security. A notice is not a prohibition. It is the step that opens the door to one.
What follows is set out in section 25.3. After consulting the Minister of Public Safety, the Minister may order a further review, and the National Security Review of Investments Regulations give 45 days from the notice for that decision. If a review is ordered, interim conditions can be imposed while it runs. Section 25.4 then puts the outcome in the hands of the Governor in Council, which may authorise the investment on terms, prohibit it, or order a divestiture. As of the reporting, Ottawa had not taken the section 25.3 step.
So the deal is not blocked. It is sitting inside a statutory clock, with the clock's owner having said out loud that it sees a national security question.
The jurisdictional objection is the whole case
Lithium Chile's answer is not that the deal is harmless. It is that the Act does not reach the deal. Argentum, on the company's account, is not a Canadian company and has no assets, no employees and no place of business in Canada. The salar is in Salta. The buyer is in Shenzhen. The only Canadian element in the transaction is the identity of the seller's parent.
That objection is narrower than it sounds, and it is also the most interesting question in the file. Part IV.1 of the Act is drafted around investments to establish a new Canadian business, to acquire control of a Canadian business, or to acquire an entity carrying on operations in Canada. Each limb of that test has a Canadian anchor built into it. Whether a share sale of a foreign subsidiary between two foreign-controlled parties supplies one is not obvious from the words.
Ottawa plainly reads it more broadly. The September 2024 amendments were designed to widen the regime's reach and lower the threshold for intervention, and the department has been more willing since to treat critical minerals held offshore by Canadian issuers as within its interest. Lithium Chile says it put the jurisdictional point before the notice was issued and got no reply.
This is where the case stops being about one salt flat. A decision either way sets the boundary of the regime for every Canadian-listed junior whose only real asset is somewhere else.
The treaty exists and it does not help
The instinctive question for anyone in this practice is whether the Chinese buyer has a treaty claim. Canada and China signed a foreign investment promotion and protection agreement on 9 September 2012, and it entered into force on 1 October 2014. China Union is on its face a covered investor.
The agreement then removes precisely this decision from the arbitration it otherwise offers. Its terms exclude from dispute settlement a decision by Canada following a review under the Investment Canada Act as to whether to approve an investment subject to review, or to permit an investment subject to national security review. The carve-out was deliberate and it was public at the time of signature. Canada has taken the same reservation in most of its investment agreements.
The result is a treaty that protects the investment once it exists and says nothing about whether it may come into existence. An investor screened out at the gate is left with domestic administrative law. In Canada that means judicial review in the Federal Court, on a record the government controls and against a standard of reasonableness that has never been generous to national security determinations.
There is a further asymmetry worth naming, because it has been in the academic literature since the agreement was signed. China's equivalent carve-out is not tied to a single named statute. It refers to its laws, regulations and rules, which is a wider reservation than Canada took for itself. That imbalance was criticised in 2012 and it has become more relevant now that Canada is the one doing the screening.
Two governments pointing in opposite directions
The political frame around this is genuinely odd. In January, Prime Minister Mark Carney visited Beijing, where the two countries announced a strategic partnership and released a Canada-China Economic and Trade Cooperation Roadmap. Ottawa used that document to welcome Chinese investment in named sectors including energy, agriculture and consumer products. China Union has pointed to the visit.
Critical minerals were not on that list. The roadmap and the notice are therefore not strictly in conflict, and a government is entitled to court capital in one sector while fencing another. But an investor reading the January communiqué and the August notice together is being asked to hold two signals that a reasonable person would find hard to reconcile.
This matters beyond the optics. Legitimate expectations arguments are built out of exactly this material, and the fact that the treaty forecloses the claim in this instance does not mean the pattern is costless. It shapes how the next Chinese bidder prices Canadian counterparty risk, and how quickly they walk when a Western junior comes looking for a cheque.
Why it matters for dispute formation
Most of the resource nationalism this publication tracks runs in one direction. A host state changes the terms after the money is in the ground, and the investor reaches for a treaty. Indonesia banning ore exports, Mexico reserving lithium, the DRC requiring domestic processing, and Washington allocating its own battery scrap are all versions of that.
This is the other direction. The state acting here is the home state, the asset is in a third country, and the measure operates on the share register rather than on the licence. The host government wants the transaction. The chokepoint is the nationality of the seller's parent.
The disputes that follow will mostly not be treaty arbitrations, because the treaty says they cannot be. They will be commercial. A long-stop date passes and a break fee is argued over. A shareholder alleges the board knew the regulatory risk and disclosed it late. A buyer says a condition precedent has failed and the seller says it was the seller's to satisfy. None of that reaches ICSID and all of it is expensive.
The practical lesson for anyone drafting now is that Investment Canada Act clearance has to be treated as a condition in its own right, in deals with no Canadian assets on either side of the table, whenever a Canadian issuer sits in the chain. Assuming otherwise was reasonable a year ago. It is not reasonable this week.
Who's exposed
Exposed on the deal it has spent nine months closing. Shareholders approved the sale of the Argentine assets by a strong majority, and the company says it received no response to its jurisdictional objection before the notice landed. It has said it will advance that position forcefully and seek all remedies available. Those remedies run through the Federal Court, not through arbitration, and judicial review of a national security decision is among the harder applications to win.
Exposed twice over, and to two different governments. It needs outbound direct investment approval from Beijing and it now needs Ottawa not to order a review. The company has pointed to the September 2024 amendments to the Investment Canada Act and to the Canada-China strategic partnership announced in January. Neither observation binds the director of investments.
Exposed to a decision taken in a capital 9,000 kilometres away, in a proceeding to which neither is party. Argentina wants this capital. Salta wants the development. Nothing in the Investment Canada Act requires Ottawa to weigh either interest, and nothing in the process gives Buenos Aires standing to be heard.
Exposed to a reading of the Act that would make a Vancouver listing travel with the rock. Hundreds of TSX and TSX-V issuers hold their only material assets in Latin America, Africa and Central Asia through foreign subsidiaries. If the sale of such a subsidiary is screenable because its parent is Canadian, the listing venue becomes a permanent consent requirement on exit.
Exposed to a pattern rather than an incident. Chinese buyers have been the marginal bid for lithium and copper assets that Western majors will not fund, and a screening regime that reaches offshore subsidiaries removes a route that was assumed to sit outside it. Expect that risk to be priced into break fees and long-stop dates rather than argued about after signing.
Exposed to the same question at one remove. Argentina's salares have drawn capital on the assumption that Argentine permitting is the binding constraint. This notice suggests a second constraint that sits in the shareholder register, and it applies whatever Argentina decides.
The historical parallel · Global Telecom Holding S.A.E. v Canada, ICSID Case No. ARB/16/16
The closest thing to a precedent for a foreign investor taking Ottawa on over its regulatory treatment of a holding. GTH brought its claim under the 1996 Canada-Egypt bilateral investment treaty over the government's handling of Wind Mobile and sought 1.32 billion Canadian dollars. In March 2020 the tribunal dismissed every claim, and an annulment committee upheld that award in September 2022. Six years, and nothing. Arizaro would begin from a worse position still, because the Canada-China agreement takes the national security decision outside arbitration altogether. GTH was at least arguing about how an existing investment had been treated. China Union would be arguing about whether it may make one.
What to watch
- Whether Ottawa orders a full review under section 25.3 within the 45-day window that the notice started, or lets it lapse and gives the parties their certainty by silence.
- Whether Lithium Chile files for judicial review of the notice itself, which would put the jurisdictional reach of Part IV.1 in front of the Federal Court rather than leaving it to departmental practice.
- Whether Beijing's outbound direct investment approval arrives first, and what China Union does if it holds a Chinese approval and a Canadian prohibition at the same time.
- Whether the parties extend the closing deadline again, and what any extension costs, since the price of delay is where the commercial dispute will start if the deal fails.
- Whether other Canadian-listed juniors with foreign salares begin disclosing Investment Canada Act risk as a distinct condition in sale agreements, which would be the clearest sign the market has repriced this.
- Whether Argentina says anything at all. Silence from Buenos Aires would be its own signal about how much leverage a host state now has over the sale of its own subsoil.
Sources
- MINING.COM - Lithium Chile's $175M China deal faces Canada scrutiny (18 August 2026)
- Investment Canada Act, Part IV.1 - Review of Investments Injurious to National Security (ss. 25.1-25.4)
- National Security Review of Investments Regulations, SOR/2009-271
- Global Affairs Canada - Canada-China Foreign Investment Promotion and Protection Agreement
- Bill C-34 - National Security Review of Investments Modernization Act
- Innovation, Science and Economic Development Canada - Investment Canada Act
- Lithium Chile Inc. - corporate disclosure
- Mondaq - The Canada-China FIPA: a comparative analysis to Canada's model FIPA
- Canada Gazette Part II - Regulations Amending the National Security Review of Investments Regulations (SOR/2022-124)
See the disputes forming before the market does.
Signal Watch tracks the developments. The monthly Intelligence Brief synthesizes all four signals into the disputes most likely to crystallize next — free.
Get the Intelligence BriefFor general information only; not legal advice, and no attorney–client relationship is formed through this article. Company names appear because the operators are exposed to a public development — not as a statement of wrongdoing or a predicted outcome. Figures are as reported by the linked sources.